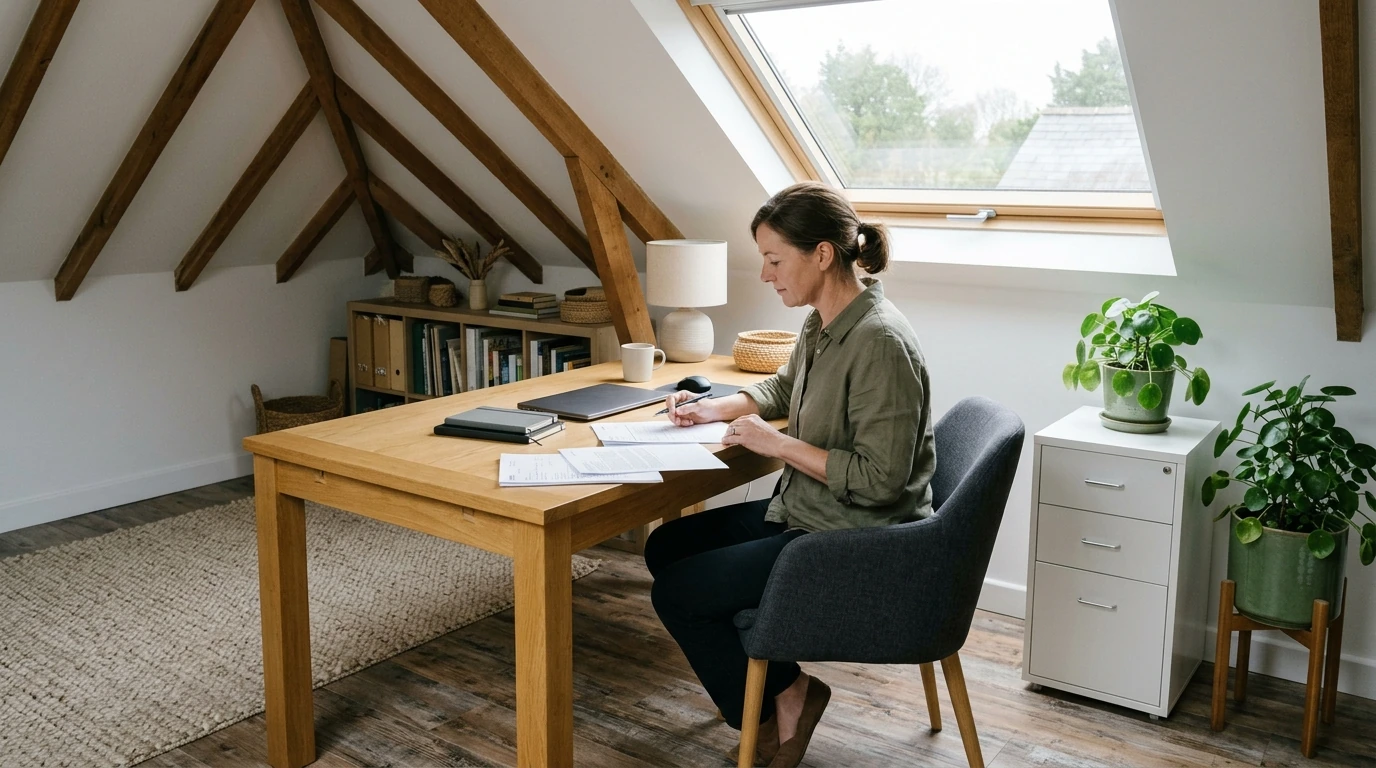
Your home office generally must be your principal place of business, a place where you regularly meet clients or customers in the normal course of business, or a separate structure used in connection with your business. A home office can qualify as your principal place of business if you use it substantially and regularly for administrative or management activities and have no other fixed location where you conduct substantial administrative or management activities.
Featured in this guide
Your Ultimate Home Office Guide | Digital Download | How to Organize a Home Office for Productivity, Focus & Style | Printable eBook & Workspace Setup Planner
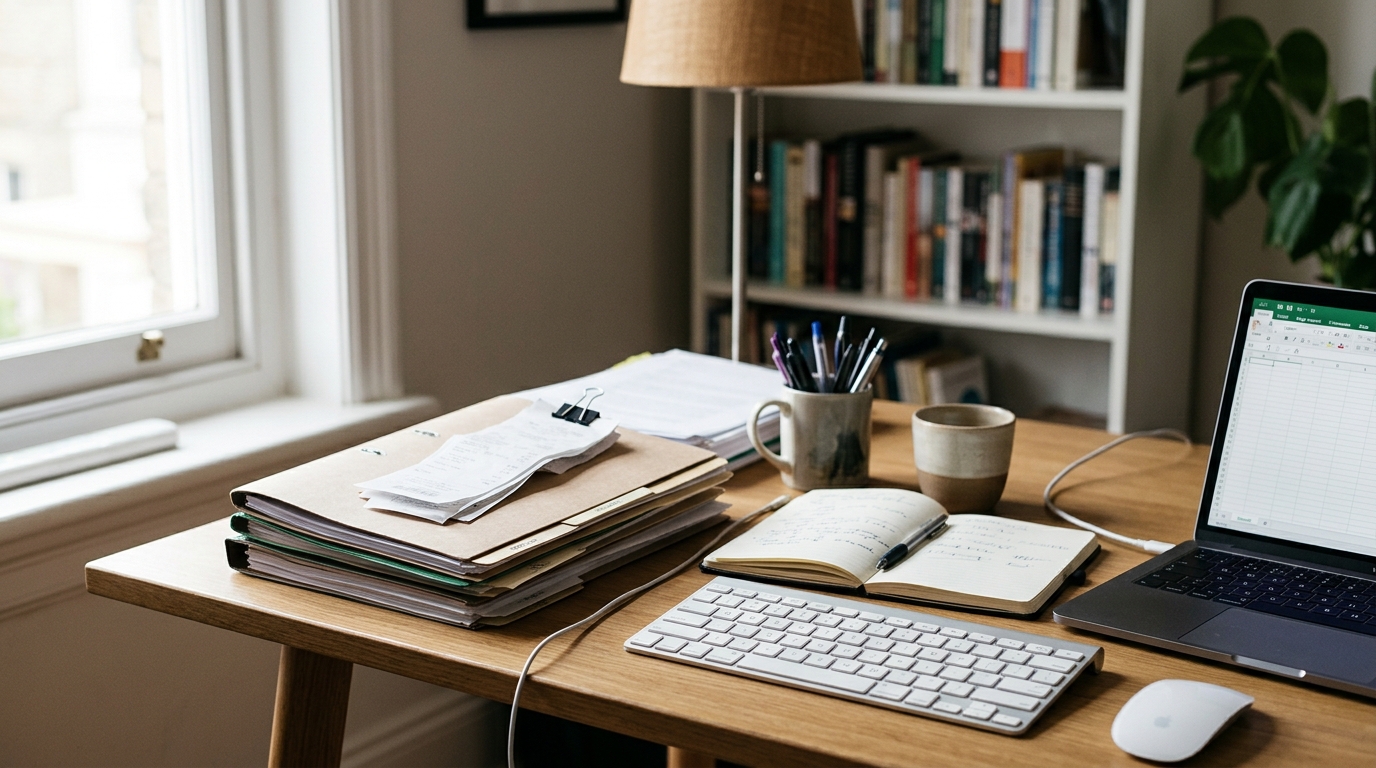
Keep documentation that supports regular, exclusive business use and your deduction, such as a floor plan, measurements, receipts, and records of your business activities; our team also recommends keeping business and personal items clearly separated in the designated area. For practical ideas, explore our home office setup guide and our featured digital download, Your Ultimate Home Office Guide, which includes a printable eBook and workspace setup planner.
FAQ
What qualifies as a home office for the IRS?
A qualifying home office is generally a clearly defined area used regularly and exclusively for your business that also meets an applicable business-use test. For example, a dedicated area used for substantial administrative work may qualify if you have no other fixed location where you conduct substantial administrative or management activities.
See if Your Ultimate Home Office Guide | Digital Download | How to Organize a Home Office for Productivity, Focus & Style | Printable eBook & Workspace Setup Planner fits your setup

Leave a comment